


Important information:
Am 10. April 2024 wurden das Kundenportal sowie der Web-Zugriff auf das Kartenkonto eingestellt. Bitte laden Sie die Swiss Bankers App herunter, um weiterhin uneingeschränkten Zugriff auf alle Dienste zu haben.
Are you a Swiss Bankers sales partner?
Hier geht es zum Partnerportal.
A holiday in Italy, a city break to Barcelona or a road trip through the USA: as soon as you’re heading abroad, the question of the right payment method quickly arises. Should you take your usual bank card with you, or is a separate card for your travel budget the better solution? In this article, you’ll find out how the Swiss Bankers Prepaid Travel Card works, what security features it offers and what you should bear in mind when making payments and withdrawing cash abroad.
 26.09.2026
 Miryana
Contents:
Imagine you’re planning a two-week holiday in Thailand and want to set a travel budget of CHF 2,000. Instead of paying for everything through your usual bank account, you top up the Swiss Bankers Travel Card with this amount before you travel. Once there, you can use it to pay for things such as your hotel, an evening meal or an excursion – each payment is deducted directly from the available card balance.
That is precisely the principle behind the Travel Card: it operates on a prepaid basis. Unlike with a traditional credit card, you do not use a credit limit, but only the balance that you have topped up beforehand. We explain in detail how prepaid credit cards work in our article “Prepaid credit cards explained: This is how they really work!”.
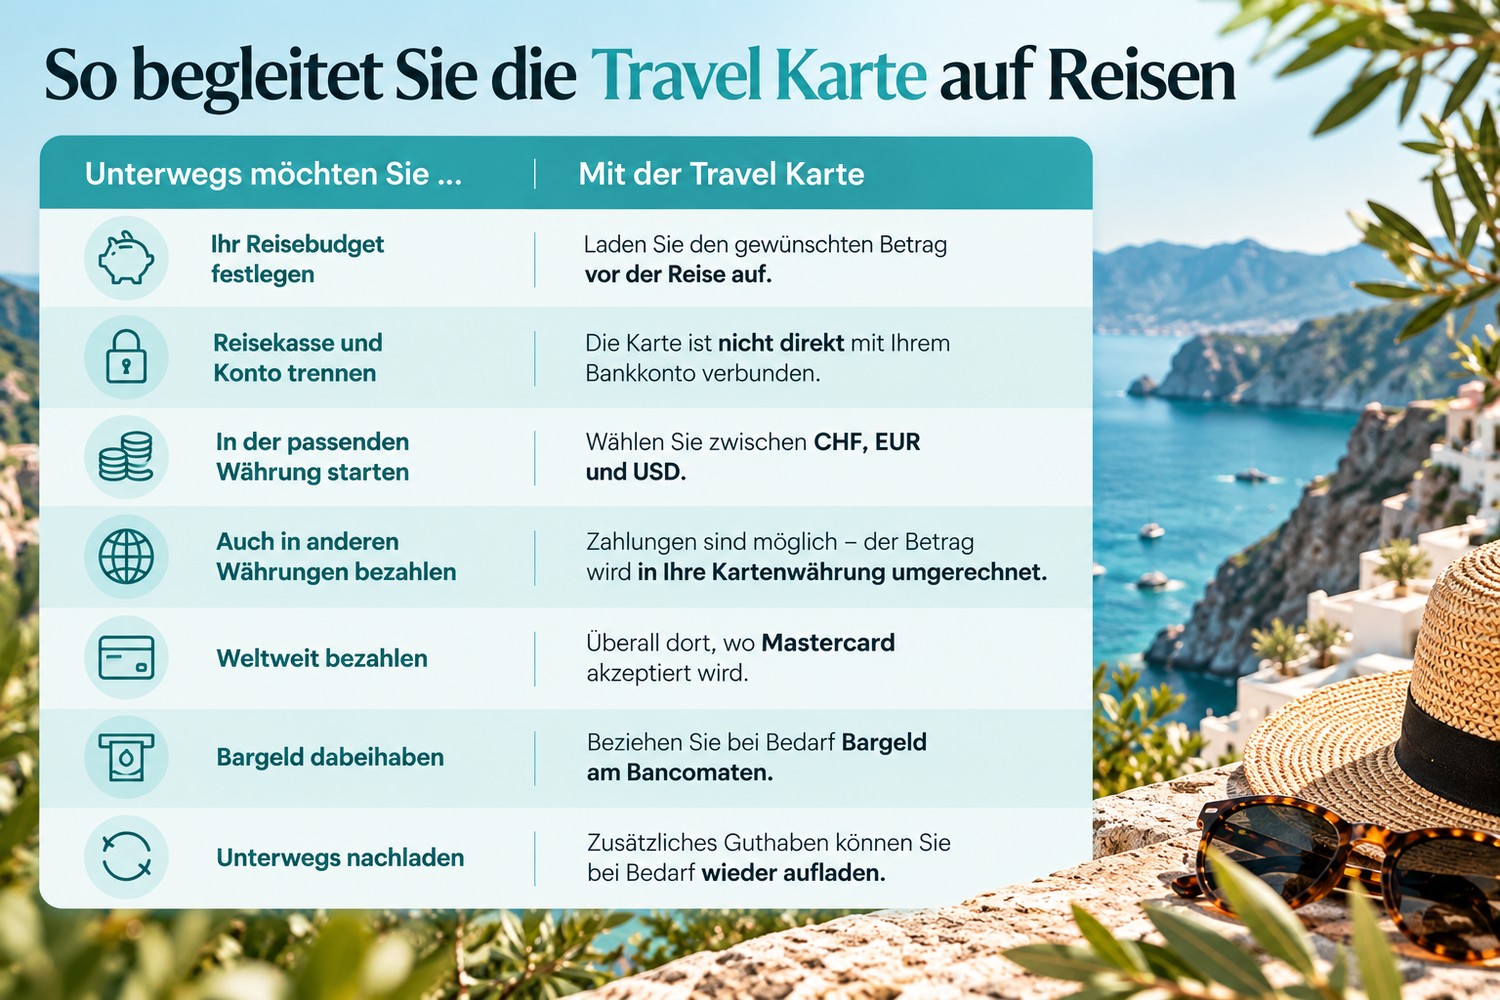
The Travel Card is not directly linked to your bank account. This allows you to manage your travel budget separately, and the card itself does not provide direct access to your everyday account. As a Mastercard, the Travel Card can be used worldwide at millions of acceptance points – such as in hotels, restaurants, shops and online stores. You can also withdraw cash from ATMs.
The Travel Card is available in CHF, EUR and USD. However, you can also make payments in other local currencies – the amount will be converted into the currency of your Travel Card.
This means you can keep your travel funds separate from your everyday bank account and decide for yourself what budget is available whilst you’re travelling.
The Travel Card isn’t just for long-haul trips. Having a separate travel budget can also be handy for a long weekend in Barcelona, a summer holiday in Italy or your first trip on your own.
In short: the Travel Card is particularly useful if you want to keep your travel funds separate from your everyday spending and decide for yourself how much money you have available whilst travelling.
Whether it’s a coffee in Rome, dinner in Bangkok or a spontaneous visit to a museum in New York: with the Travel Card, you can make payments worldwide wherever Mastercard is accepted – in shops, restaurants, hotels or online. Contactless and mobile payments are also available. You can also withdraw cash whilst travelling. The Travel Card can be used at cash machines both at home and abroad. The amount you can withdraw per transaction depends, amongst other things, on the cash machine operator and the country.
An important tip for payments and cash withdrawals abroad: where possible, choose the local currency. If, for example, you are offered the option in Thailand to pay the amount directly in Swiss francs, you should choose baht instead. This way, you avoid an additional conversion by the retailer or ATM operator. Swiss Bankers also expressly recommends this for the Travel Card.
Good to know: Fees may apply for cash withdrawals. The amount may vary depending on the product, card currency and where the card is used. You can find the current terms and conditions in Swiss Bankers’ fee overview.
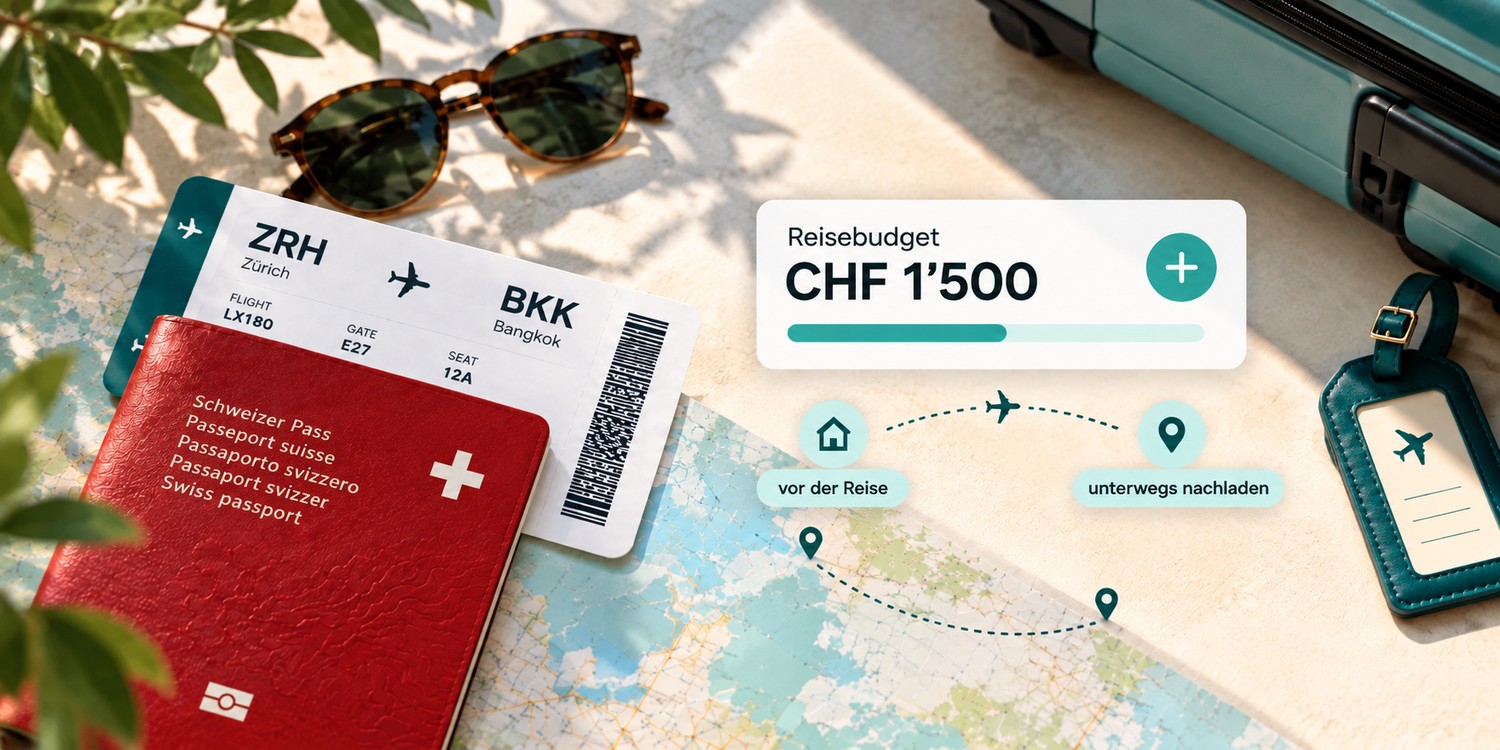
Top up CHF 1,500 for your travel budget just before you set off – or top up whilst you’re away if your holiday ends up costing a bit more: there are various ways to add credit to your Travel Card.
The minimum top-up amount is CHF/EUR/USD 100, and the maximum is CHF/EUR/USD 10,000. Depending on the top-up method, the credit becomes available at different speeds: quick top-ups via the app can be credited within around 15 minutes, whilst a bank transfer via e-banking usually takes longer.
A top-up fee of 1.5 per cent of the top-up amount is usually charged. Depending on the top-up method chosen, additional or different fees may apply. You can find the current fees and terms and conditions in the Swiss Bankers fee overview.
If your Travel Card is lost or stolen, you can block it immediately via the Swiss Bankers app. In addition, geoblocking allows you to disable transactions in specific regions or continents. Swiss Bankers will replace a lost physical card free of charge by courier worldwide. Digital cards are normally replaced within one working day.
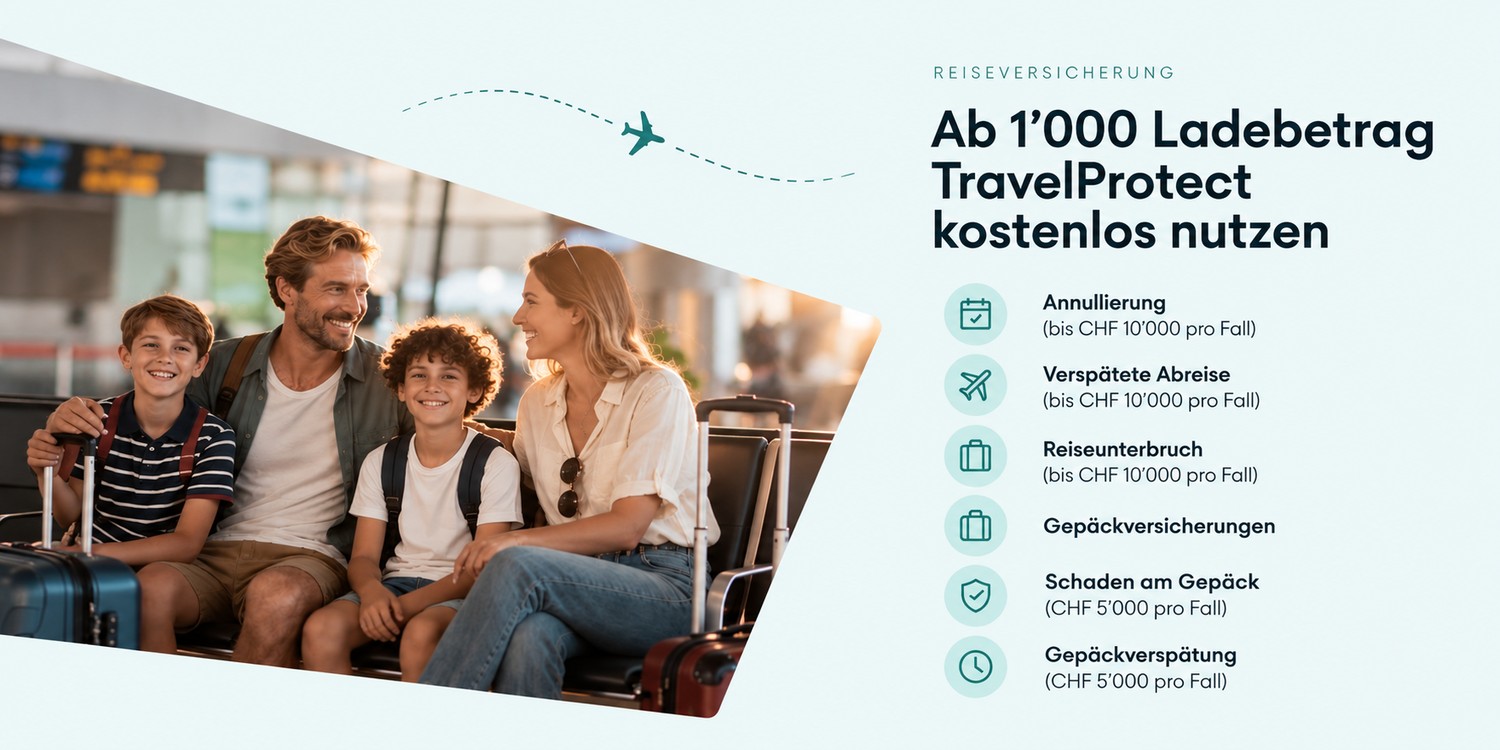
TravelProtect offers additional cover. Once you have topped up your card with at least CHF/EUR/USD 1,000, you can activate the travel cover in the app and use it free of charge for twelve months. Depending on the claim, cover may include, amongst other things, benefits in the event of travel cancellation, trip interruption or luggage issues.
Important: The actual insurance cover is subject to the applicable insurance terms and conditions. These also set out the eligibility criteria, exclusions and benefit limits. Furthermore, TravelProtect must be activated before the trip is paid for, and the trip must be paid for in full using the insured Travel Card.
With the Swiss Bankers Travel Card, you can keep your travel funds separate from your everyday bank account and pay flexibly whilst on the move, withdraw cash and top up the card as and when needed. Security features in the app and TravelProtect complement the card with practical services for when you’re on the go.
This way, you can keep track of your travel budget and be flexibly prepared for your travels.

© Swiss Bankers 2026


 Compare cards and conditions

